
 Taxes on Severance Pay
Also listed in:Money Management > Taxes
This tool calculates the income tax and resident tax on severance pay.
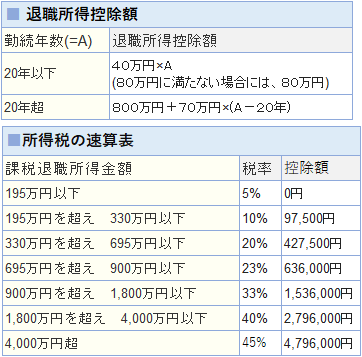
- Retirement income
- General retirement income = (Severance pay − Retirement income deduction) × 0.5
- ※For severance pay for service of 5 years or less (short-term retirement allowances, etc.) from Reiwa 4 onward, the rule taxing only one-half of the amount does not apply to the portion exceeding 3 million yen after subtracting the retirement income deduction.
- Specified retirement income (officers, etc. with 5 years of service or less) = Severance pay − Retirement income deduction
- ※The retirement income deduction for specified officers' retirement allowances, etc. is 400,000 yen × Years of service as a specified officer, etc.
- ※This calculator cannot handle cases where the service period for specified officers' retirement allowances, etc. overlaps with the service period for general retirement allowances, etc.
- Taxes
- Income tax (including the Special Income Tax for Reconstruction) = (Retirement income × Tax rate - Deduction) × 1.021
- Municipal tax = Retirement income × 0.06
- Prefectural tax = Retirement income × 0.04
- Fractions of less than 1 yen are rounded down.
- Severance pay is taxed separately to reduce the tax burden.
- The Special Income Tax for Reconstruction (2.1% of income tax) is added to income tax.
- Resident tax is 10% (Municipal tax 6% + Prefectural tax 4%).
※This site assumes no responsibility for calculation results or other information. We do not provide individual consultations.
- Related links

No customer feedback for this calculation yet.