
 Taxes on Temporary Income
Calculates the income tax on temporary income.
"Temporary income" refers to income other than that arising from continuous activities conducted for profit, specifically one-time income that does not constitute compensation for labor or services, nor consideration for the transfer of assets. (From National Tax Agency materials)
| (1) Prizes from contests or raffles (excluding those received in connection with business activities) (2) Payouts from horse racing or bicycle racing (excluding those arising from continuous activities conducted for profit) (3) Lump-sum payments from life insurance (excluding those received in connection with business activities) and maturity refunds from property insurance, etc. (4) Money or goods gifted by a corporation (excluding those received in connection with business activities or those received on a continuous basis) (5) Rewards received by finders of lost property or discoverers of buried treasures, etc. (6) Grants received to cover expenses related to the transfer of assets, etc., that were not used for the expenditures specified as the purpose of the grant |
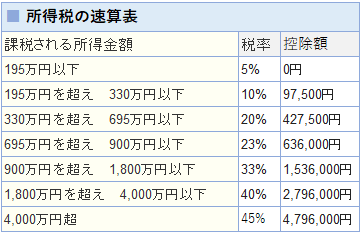
- Calculation Method
- Amount of Incidental Income = Total Income − Amount Expended to Earn That Income − Special Deduction (up to 50 ten thousand yen)
- Taxable Amount = Amount of Incidental Income × 1/2 + Other Income
- Amount of Income Tax = (Taxable Amount × Tax Rate – Deductions) × 1.021 (Special Income Tax for Reconstruction)
- Starting in Heisei 25, a Special Income Tax for Reconstruction (2.1% of the income tax) will be added to the income tax.
*This site assumes no responsibility whatsoever for calculation results or other information. Furthermore, we do not provide individual consultations.
- Related links

No customer feedback for this calculation yet.